Meet your lender
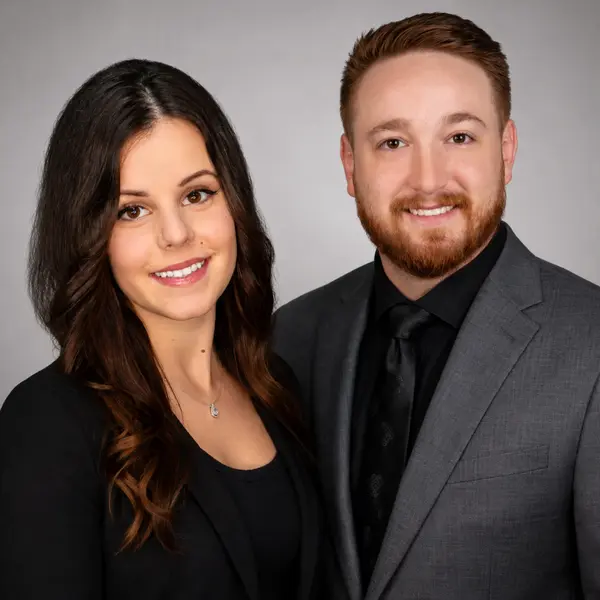
Amy Pohl
Amy Pohl, with the Pohl Home Team, brings more than 28 years of Mortgage Lending and Banking experience, complemented by an MBA in Business Finance from Arizona State University. She is not only a seasoned lender but a financial strategist, dedicated to aligning the right home loan with your long-term financial goals. Amy’s undeniable passion for the real estate and mortgage industries, coupled with her unwavering commitment to her clients and referral partners, has earned her a trusted reputation within the community. Her dedication to education, transparency, and excellence has resonated with home buyers, professionals, and local REALTORS®, many of whom frequently refer new clients to her.
Read Amy’s full bio
Amy began her career in 2000 as a licensed financial banker, holding Series 6 and 63 certifications, where she created personalized financial strategies for clients’ short- and long-term goals. Realizing that a home is often her clients’ largest asset, she transitioned into mortgage lending to help clients make informed decisions about homeownership and how it fits into their broader financial strategy.
“I’m committed to educating my clients on their home loan options, explaining the pros and cons of each choice. My goal is to provide the knowledge and confidence you need because without all the information, how can you make a fully informed decision? Whether your goal is to retire mortgage-free or find the right loan for your unique situation, I’m here to guide you every step of the way.”
At the Pohl Home Team, you can expect a clear and smooth process, with a dedicated team supporting you at every stage. Whether you are a first-time home buyer, self-employed, have less-than-perfect credit, looking to renovate, a high-net-worth family, or someone needing to leverage down payment assistance, just to name a few, Amy and her team provide thorough pre-approvals, on-time closings, and competitive rates. Amy prides herself on their motto, “You can expect an experience defined by honesty and hard work,” and she shows this through action every day. She’s committed to earning your trust, not just through words, but through the results she delivers.
Amy’s success is built on your results. She and her team are committed to delivering unparalleled service and a seamless, unforgettable process. “Buying a home is one of the biggest financial commitments in life, and I am motivated to exceed expectations. It’s more than just a house—it’s a home.”
Amy looks forward to meeting you and earning your trust!
The options
Which Loan Is Right for You
Most buyers qualify for more than one. A good lender will run the numbers side by side and show you what each one actually costs per month.
Conventional
The most common loan, and usually the cheapest over time if you have decent credit. As little as 3% down for qualified first-time buyers, 5% for most others.
Good to know: mortgage insurance comes off once you reach enough equity, unlike FHA. 2026 Maricopa County limit is $832,750.
FHA
Built for buyers whose credit or savings aren't where they'd like them yet. 3.5% down, and the credit requirements are more forgiving than conventional.
Good to know: mortgage insurance usually stays for the life of the loan, so many buyers refinance out of it later. 2026 Maricopa County limit is $557,750.
VA
For eligible service members, veterans and surviving spouses. No down payment, no monthly mortgage insurance, and competitive rates.
Good to know: there's a one-time funding fee, waived for some veterans. With Luke Air Force Base in the West Valley, we write these often.
USDA
Zero down, for homes in areas the USDA designates as rural. Income limits apply, and they're more generous than people expect.
Good to know: parts of the outer West Valley qualify. Ask us to check a specific address before you rule it out.
Jumbo
For loan amounts above the conforming limit. Expect a larger down payment, stronger reserves and more documentation.
Good to know: terms vary a lot between lenders on jumbo, so this is one where shopping genuinely pays.
Not sure?
You don't have to pick. Tell a lender your situation and let them show you what you qualify for. It costs nothing to find out.
Ask Denitsa & Christian →Loan limits shown are 2026 figures for a one-unit home in Maricopa County and change annually. Program terms, rates and eligibility are set by the lender, not by us. This is general information, not a loan offer or a commitment to lend.
How it works
Pre-Approved in About a Week
Most of it is paperwork you already have. The conversation itself usually takes twenty minutes.
01
Talk to a lender
A short call about your income, your debts and how much you want to put down. No credit pull yet if you'd rather not.
02
Send your documents
Typically two months of pay stubs and bank statements, two years of W-2s or tax returns, and a photo ID. Self-employed buyers send a bit more.
03
Get your letter
The lender verifies everything and issues a pre-approval letter with a number on it. That letter is what makes your offer credible.
04
Set your real budget
What you're approved for and what you want to spend are two different numbers. We'll help you decide which one to shop at.
Worth knowing
Shopping several lenders inside a short window counts as one credit inquiry for scoring purposes, so comparing offers doesn't punish your score the way people fear. Get at least two Loan Estimates and compare them line by line — rate is only part of the cost.